- Experiences closely tied to identity may be more resistant to cuts. Fandom shows that engagement can continue through low-cost or free participation, while paid spending remains optional. Signal to monitor: the balance between free and paid participation in future fandom surveys.
- Consumers may maintain a category while downgrading its frequency or tier. Value-for-money preferences and plan downgrades in the telecommunications category provide a basis for testing this possibility in tickets, subscriptions, and travel. Signal to monitor: the frequency and value of leisure spending in transaction data.
- The experience-spending gap between income groups may widen. If spending among higher-income groups continues to grow while spending among lower- and middle-income groups slows, paid experiences may become increasingly concentrated among consumers with greater budget flexibility. Signals to monitor: spending changes by income group and Bank Indonesia’s Current Economic Conditions Index.
- Communities may help sustain engagement. Fandom and wellness data show participation in community-based activities, although they do not yet prove an impact on spending retention. Signal to monitor: community participation rates in future wellness and fandom surveys.
- Affordable alternatives may become an important entry point for younger consumers. YouGov data show that younger consumers are more likely to cut discretionary lifestyle spending, while PwC data indicate that most still have room in their income for savings and spending beyond essential needs. Signal to monitor: differences in experience spending by age and income, including Indonesia-specific releases from the UOB ASEAN Consumer Sentiment Study.
Experience Economy: Why Consumers Still Spend on Entertainment?
22 min read

Intinya Sih
- Tekanan biaya hidup dirasakan 84% responden Indonesia; kebutuhan pokok menjadi prioritas, sementara 37% berencana mengurangi rekreasi dan aktivitas sosial.
- Hiburan tetap dipilih secara selektif karena bernilai emosional, identitas, dan sosial; 54% Gen Z penonton konser mencari hiburan, sedangkan 47% mencari pelepas stres.
- Kapasitas finansial menentukan pilihan: belanja kelompok berpendapatan tinggi masih tumbuh, sementara kelompok menengah-bawah melambat; konsumen cenderung menurunkan tingkat pengeluaran, merencanakan anggaran, dan mempertahankan pengalaman paling penting.
This section summary was AI-assisted and reviewed by our editorial team.
In late April 2026, as global developments drove fuel prices higher and raised concerns about the cost of living, YouGov surveyed 2,010 Indonesian adults about changes in their spending and mobility habits. Responses regarding travel frequency were evenly split: 32% said they were travelling less often, while another 32% said they were travelling more frequently.
Two months later, a Jakpat survey of 1,865 respondents revealed another side of this tension. Among Gen Z respondents who attended concerts in 2026, 47% cited stress relief as one of their reasons for going to a concert. Financial pressure is real. At the same time, some consumers continue to choose experiences that offer entertainment and emotional value.
This article explores one question: why does spending on entertainment, hobbies, and experiences still have a place in consumer decisions when purchasing power is under pressure? Data from 2026 point to a more interesting answer than the simple resilience of the experience economy. Consumers are becoming more selective about which forms of enjoyment are worth keeping, and these choices differ by income group and age.
Enjoyment Amid a Tightening Budget
Cost-of-living pressures are widespread. According to YouGov’s survey conducted on April 23–27, 2026, 84% of Indonesians said they personally felt the impact of rising fuel prices, while 47% described the impact as significant. A total of 65% reported feeling financially stressed, including 11% who felt very stressed and 54% who felt fairly stressed.
Essential expenses are bearing the greatest impact. Some 61% of respondents identified food and grocery spending as the most affected expense, followed by daily commuting costs (32%) and utilities (31%). Leisure activities were mentioned by 17% of respondents. However, when asked about their plans, 37% intended to reduce recreational activities and social outings, while 34% planned to cut spending in other categories.
These two sets of figures reveal different sides of household budget adjustments. Food and grocery spending was most frequently identified as an expense already affected by rising costs, while recreation and social activities were most frequently included in plans for future reductions. This suggests that cost pressures are being felt across various expenses, while recreational activities are among the categories consumers are considering when reassessing their budgets. The 37% figure reflects intentions expressed in April 2026, indicating how households were considering adjustments rather than measuring actual spending reductions.
Transaction data through early May 2026 point in a similar direction. Citing Kontan, Mandiri Institute recorded nearly 6% year-on-year growth in supermarket spending, up from 3.3% during the same period a year earlier, while spending in leisure and electronics remained relatively subdued. This does not indicate a decline in leisure spending. Rather, its growth lagged behind supermarket spending, consistent with household spending priorities shifting more towards everyday necessities.
Consumer sentiment presents a more nuanced picture. Bank Indonesia’s September 2026 Consumer Survey recorded a Consumer Confidence Index (CCI) of 118.1, remaining in optimistic territory. This optimism was supported by the Consumer Expectations Index, which rose to 128.7. Meanwhile, the Current Economic Conditions Index declined from 109.4 to 107.5, although it remained in the optimistic zone. Consumers continued to hold positive expectations about future conditions, while their assessment of the current economy weakened slightly. This difference provides context for the spending caution reflected in the YouGov and Mandiri data.
A similar pattern emerged at the regional level. UOB’s ASEAN Consumer Sentiment Study 2026, which surveyed 5,000 consumers across five ASEAN countries in June 2026, including 1,000 respondents from Indonesia, found that 63% of consumers across the region were concerned about rising living costs, up three percentage points from 2025. The largest net increases in spending were recorded for utility bills (16%) and groceries (12%). UOB also noted that some consumers across the region continued to make room for experiences, with the strongest spending growth reported in entertainment, concerts, events, and festivals. However, these findings were presented without specific figures or country-level breakdowns, so they can only be interpreted as a regional ASEAN overview.
Three things need to be distinguished when reading these findings: the desire to enjoy an experience, the decision to participate, and the ability to pay for it. Cost pressures affect the available spending room, while emotional and social motivations can remain part of consumers’ considerations when choosing activities. The question is: what makes certain experiences worth paying for?
From Stress Relief to Self-Investment
Concerts offer an example of why consumers seek certain experiences. Jakpat’s Music Concert Trends & Fan Behaviors 2026 survey, involving 1,865 respondents between June 29 and July 1, 2026, found that among Gen Z respondents who attended concerts in 2026, 54% went for entertainment and 47% to relieve stress. Other reasons included seeing their favourite musicians (45%) and experiencing the excitement of live performances (43%). Only 7% cited following trends. These motivation figures were published by GoodStats, citing the Jakpat report.
This distribution offers a glimpse into what concertgoers value. Entertainment and stress relief were mentioned more frequently than the desire to follow trends. For some audiences, concerts provide an opportunity to enjoy music, experience the atmosphere of a live performance, and take a break from their routines. A ticket purchased for these reasons carries emotional value beyond simply gaining access to see a musician perform live.
This interpretation is consistent with the reported motivations, although the survey does not measure spending levels or prove that emotional value makes consumers more resistant to price pressures. The respondent base also needs to be considered: these figures come from Gen Z respondents who had already attended concerts, and Jakpat did not disclose the size of this subgroup. Therefore, the findings explain the motivations of Gen Z concertgoers, not the entire Gen Z population.
Considerations around personal well-being can also be seen beyond entertainment. PwC’s Voice of the Consumer 2026 survey of 503 Indonesian respondents, conducted in February–March 2026 and released on September 3, 2026, found that 51% of consumers identified stress reduction and mental health as their main health-related goals. Another 41% considered personal development an important goal, while 58% regularly engaged in physical fitness activities.
These findings show that personal well-being encompasses several needs, expressed through different types of activities. Concerts offer entertainment in a single occasion, while fitness and personal development involve activities that can be pursued regularly. All three may provide personal value, but they should not be treated as the same type of spending.
Younger consumers appear to be more active in fitness activities. According to PwC, 61% of younger consumers exercise regularly, compared with 43% of older consumers. Some 31% of younger consumers pay for gym memberships, fitness classes, or personal trainers, nearly three times the proportion among older consumers (11%). This difference highlights variations in wellness participation and spending across age groups.
Emotional value helps explain why consumers want to enjoy certain experiences. Some experiences go a step further by becoming part of how people see themselves.
Fandom and the Two-Layer Economy
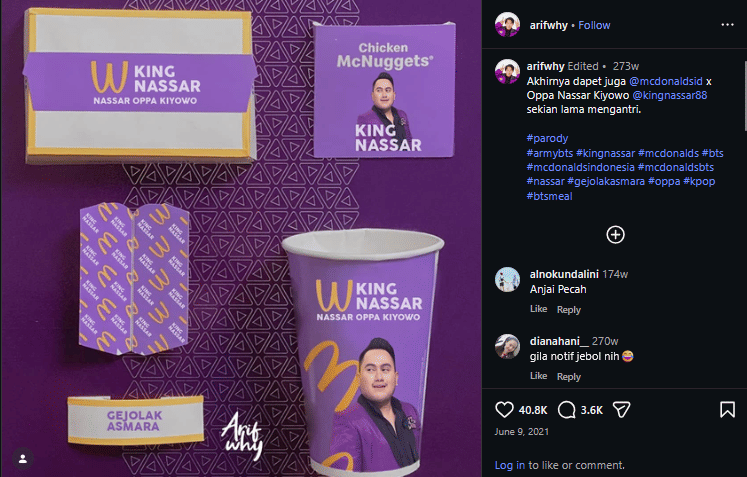
Music fandom illustrates how identity shapes spending decisions. In its public summary of the same survey, 2026 Music Trends Snapshot, Jakpat found that respondents were more likely to support their favourite musicians through unpaid activities. Some 50% did so by streaming music, while 46% followed musicians’ social media accounts. Buying merchandise was mentioned by 15%, while purchasing physical albums was reported by 12%.
When fans decide to make purchases, the items they choose can also carry symbolic meaning. Jakpat reported that seven in ten fans collected T-shirts featuring their favourite musicians, followed by jackets (44%), stickers (40%), and keychains (38%). Among Gen Z respondents, 44% collected photocards of their favourite artists. Jakpat’s public summary does not specify the respondent base for each merchandise collection figure, so these numbers are best read as an indication of popular types of fan merchandise. The value of these items may lie in the attachment they represent, beyond their practical functions.
This pattern can be understood as a two-layer economy. The core layer of engagement takes place through low-cost or free participation, while the paid layer remains optional. Jakpat’s data do not measure changes in fan behaviour before and after budget pressures, so the resilience of fandom under such pressures cannot yet be established. However, the available figures show that fan engagement does not always require spending. This structure gives fans room to adjust their purchases without necessarily giving up the identity associated with their fandom.
The same logic of identity extends to travel. Jenius Study 2026, published on February 26, 2026, involved 300 respondents through online surveys and in-depth interviews conducted between November 2025 and January 2026. The study described how Gen Z views travel as an extension of personal interests and self-expression, including visiting places associated with their interests or idols. These findings are qualitative and largely reflect habits in 2025. Nevertheless, they show that identity-driven consumption extends beyond collectible merchandise.
Identity is rarely experienced alone. For many consumers, the value of an experience is also connected to the opportunity to build relationships with others.
Communities Strengthen the Value of Experiences
Social invitations are one of the reasons people attend concerts, although they account for a smaller share than other entertainment and emotional motivations. Among Gen Z respondents who attended concerts, 22% went because someone invited them, while 16% attended to interact with musicians. In terms of community involvement, Jakpat recorded that 14% of respondents had officially joined a fanbase. Its public summary also reported that 77% said they had joined local musician fan communities. However, the summary does not clearly specify the respondent base for the 77% figure, so the two figures cannot be directly treated as measurements of the same group.
These findings suggest that music experiences have a social dimension beyond the decision to purchase a ticket. An invitation can be one reason someone attends, while a community provides space to continue engaging after becoming familiar with a musician or a particular fandom. Whether community members are more likely to maintain their spending when budgets become tighter has not been measured by the available data. This relationship remains a hypothesis worth testing.
Interest in shared activities is also reflected in PwC’s survey. Some 25% of Indonesian consumers expressed interest in social, community, and personal development activities that support a healthy lifestyle. Meanwhile, 12% regularly participated in community-based wellness activities. The proportion was 13% among younger consumers and 7% among older consumers.
These two figures measure different things: interest in certain activities and regular participation in community-based wellness activities. Since their measurement scopes differ, they cannot be used to calculate the gap between interest and actual participation. However, the participation data show that regular involvement in community-based wellness activities is still reported by a relatively small share of respondents.
At a broader scale, the social dimension can also be observed through domestic mobility. Statistics Indonesia (BPS) recorded 938.84 million domestic tourist trips between January and September 2026, an increase of 4.10% compared with the same period a year earlier. This figure was included in BPS's statement on November 2, 2026, and reported by the Indonesian Government Communications Agency.
Monthly developments show changes influenced by the travel calendar. In March 2026, which coincided with the Eid al-Fitr period, domestic trips reached 126.34 million, up 42.10% year on year. In April 2026, the number declined to 97.55 million trips. This April figure was also 24.14% lower than in April 2025. Therefore, the decline from March to April represents a month-on-month change, while the 24.14% figure represents a year-on-year comparison.
The increase in travel during the Eid period is consistent with higher public mobility for various purposes during the holiday season, including homecoming trips and family gatherings. However, domestic tourist trip data cover a range of purposes and do not provide a detailed breakdown of trips for recreation, family visits, or other needs. Therefore, these figures are better understood as an indicator of domestic mobility rather than a measure of spending on experiences or recreation.
Travel growth should also be viewed across comparable periods. Throughout 2025, domestic tourist trips grew by 17.55% to approximately 1.2 billion trips. Meanwhile, the number of trips in January–September 2026 increased by 4.10% compared with the same period a year earlier. Both figures indicate that domestic mobility remains substantial, although cumulative growth during the first nine months of 2026 was more moderate than the full-year growth recorded in 2025.
Emotional value, identity, and social connections help explain some of the reasons experiences remain attractive to consumers. The next question is how these choices are aligned with financial capacity. At this point, differences in available budgets begin to determine how much consumers can maintain the experiences they want.
New Rules for Choosing Enjoyment
Data from 2026 reveal at least four patterns that can help explain how consumers negotiate enjoyment with their financial capacity.
Downgrading Before Opting Out
Consumers expect every rupiah spent to deliver value. When choosing health products and services, 77% of Indonesian consumers in PwC’s survey prioritised value for money, while 64% identified price as a key factor.
Data on responses to price increases offer another clue about consumption adjustments. In a survey published on October 31, 2026, Jakpat asked respondents what they would do if their telecommunications provider raised data plan prices. Some 50% said they would stay with the same provider but switch to a cheaper plan or a smaller data allowance, while only 3% said they would immediately switch providers. The tendency to downgrade was stronger among Gen Z (54%) than Gen Y (46%).
These findings reflect hypothetical responses in the telecommunications category, and Jakpat does not disclose the sample size on its public webpage. Therefore, the data are used as an analogy for an adjustment mechanism: when prices rise, some consumers choose to reduce their level of consumption before considering a change of provider. Whether concertgoers or travellers behave in the same way still needs to be tested using data from those specific categories.
Planning Ahead
Experiences that require substantial spending can be managed as planned financial decisions. Jenius Study 2026 found that more than half of respondents prepared their travel budgets three months before departure. The study also described how Gen Z tends to secure as much funding as possible in advance to have greater flexibility while travelling.
Since the data were collected between November 2025 and January 2026, the findings reflect habits established before fuel price pressures intensified in 2026. Therefore, travel planning can be understood as part of how consumers manage spending on experiences, rather than a direct response to this year's price increases.
Keeping the Core, Letting Go of the Extras
PwC’s data show that not all consumers actively set aside a dedicated budget for health and wellness activities. Only 35% of respondents actively allocated a specific budget for these activities, even though several health-related goals ranked highly among their priorities.
When viewed alongside the two-layer economy pattern in fandom, these findings raise the possibility that consumers maintain the parts of an experience they consider most important while postponing additional spending that can be delayed. In fandom, for example, engagement can continue through streaming and social media, while purchasing merchandise remains an optional expense. This is an interpretation of participation patterns and budget allocation, not proof that all consumers follow the same approach.
Financial Capacity Determines How Selective Consumers Become
Spending adjustments are not evenly distributed. Citing Kontan, Mandiri Institute recorded 5.3% year-on-year spending growth among higher-income groups in 2026, up from 3.1% in the previous year, particularly in premium segments such as department stores and premium e-commerce. Meanwhile, spending among lower- and middle-income groups slowed. These figures reflect Mandiri Institute's assessment through early May 2026, based on its customer transaction data.
Age adds another layer. YouGov found that younger consumers were more likely to reduce discretionary lifestyle spending, while lower-income groups were most affected in essential spending categories such as groceries. On the other hand, PwC found that 64% of younger consumers still had sufficient income to save and spend beyond essential needs, compared with 48% of older consumers.
These findings describe different dimensions. YouGov measures consumers’ tendency to cut lifestyle spending, while PwC measures whether their income is sufficient to save and spend beyond essential needs. The available data also show differences in wellness habits and spending across age groups, as well as differences in spending growth across income groups.
Based on these findings, reallocation can be proposed as one hypothesis to explain younger consumers’ behaviour. They may cut certain lifestyle expenses while retaining room for other spending they consider important. However, the data do not directly show which spending categories are maintained or reduced by the same group of consumers.
A similar tension can be seen among higher-income groups. YouGov reported that higher-income consumers were more likely to cut back on dining out and entertainment, while Mandiri data showed that overall spending among higher-income groups continued to grow. These findings do not contradict each other because they measure different aspects of spending. Even consumers with greater financial flexibility can be selective about which expenses they maintain.
So, Why Are Consumers Still Willing to Pay?
Data from 2026 offer a more precise answer than simply saying that “consumers still enjoy having fun.” Experiences remain relevant to consumption decisions because they can serve functions that consumers consider important: relieving stress, expressing identity, and maintaining social connections. Data on concert motivations, fandom participation, and community activities illustrate these different forms of value. However, the relationship between these functions and the resilience of experience spending compared with practical purchases remains an analytical argument, not a direct measurement.
Enjoyment, however, still needs to be adjusted to financial capacity. Cost pressures encourage consumers to consider prices, plan spending in advance, and choose the parts of an experience they consider most valuable. The degree of selectivity differs by income group and age. Mandiri data show that spending among higher-income groups continued to grow, while spending among lower- and middle-income groups slowed. YouGov also found that younger consumers were more likely to reduce discretionary lifestyle spending, although PwC data show that most younger consumers still had sufficient income to save and spend beyond essential needs.
The available data are not sufficient to conclude that experience spending in Indonesia is growing across the board. What they reveal instead is increasingly selective decision-making around the type, frequency, and level of spending consumers consider worthwhile.
Reading the Direction of Experience Spending in 2027
Based on patterns observed in 2026, five hypotheses are worth testing in 2027. These are forward-looking interpretations, not established findings.
For Brands
For brands, these findings point to one principle: provide flexible pricing options within the same experience. Jakpat’s data on data plans show that some respondents prefer downgrading rather than immediately switching providers. This finding is only a cross-category analogy, so similar strategies for concerts, travel, and entertainment still need to be tested. Nevertheless, brands can consider tiered tickets, partial-access packages, or digital alternatives for consumers with different budget levels.
The second principle concerns value structure. Fan support is more frequently reported through channels such as streaming and social media, while merchandise and physical album purchases involve a smaller proportion of respondents. Therefore, paid products and experiences need to offer clear symbolic value in addition to their practical functions. Communities can also provide a space to sustain consumer engagement after the initial experience, although their impact on purchase retention still needs to be measured.
Finally, strategies need to be differentiated according to financial capacity. Mandiri data show that spending among higher-income groups continues to grow, while spending among lower- and middle-income groups has slowed. A single pricing proposition for all segments may fail to address the needs of consumers with different levels of budget flexibility.
Decision question: If consumer budgets shrink by 20%, which part of the experience you offer would they still choose to keep?
Signal to monitor: Growth in the leisure category in transaction data, broken down by income group.
For Policy
Differences in spending growth across income groups have implications beyond the market. If paid experiences become increasingly difficult to afford for consumers with limited budgets, access to recreation, sports, and shared activities may also vary according to financial capacity.
Affordable public recreational spaces, such as sports facilities, parks, and community activities, can expand public access to activities with emotional and social value. Providing these facilities can also offer alternatives for people who do not always have the budget to participate in paid experiences.
Another challenge lies in the data. This article cannot yet determine how much Indonesians spent on gaming, digital subscriptions, or dining out in 2026 because open data for these categories are not available. More comprehensive recreational spending statistics would help policymakers identify changes in discretionary consumption more quickly and accurately.
Data Notes
This article uses data collected or published in 2026 that are publicly accessible without registration or payment. Several limitations should be noted:
- Data on concert attendance motivations are based on Gen Z respondents who attended concerts in 2026; the size of this subgroup has not been disclosed.
- Jakpat’s public summary does not specify the respondent base for each figure related to merchandise and fanbase collections.
- The full Jakpat Music Concert Trends & Fan Behaviors 2026 report requires users to submit personal information to download. Therefore, this article only uses figures available on the public webpage.
- Jakpat’s findings on data plans reflect hypothetical responses in the telecommunications category and are used as an analogy.
- UOB’s findings on entertainment, concerts, and festival spending apply to the ASEAN region and are not available specifically for Indonesia.
- Jenius Study 2026 collected data between November 2025 and January 2026, involving 300 respondents.
- Mandiri Spending Index data are cited from media coverage and cover the period up to early May 2026.
- The figure of 77% regarding local musician fan communities is not accompanied by a clearly specified denominator in Jakpat’s public summary.
- Domestic tourist trip figures measure mobility for various purposes and do not specifically measure recreational spending.
- March and April 2026 travel figures use two different year-on-year comparisons: March recorded a 42.10% increase compared with March 2025, while April recorded a 24.14% decrease compared with April 2025.
- Open 2026 data on spending on gaming, digital entertainment subscriptions, and dining out are not yet available.
References
- Badan Komunikasi Pemerintah RI. (2026, November 2). Kunjungan wisatawan asing ke RI tertinggi dalam 6 tahun, capai 12 juta orang Januari–September. Accessed November 5, 2026, from https://bakom.go.id/kunjungan-wisatawan-asing-ke-ri-tertinggi-dalam-6-tahun-capai-12-juta-orang-januari-september/
- Badan Pusat Statistik. (2026a, May 4). Maret 2026, kunjungan wisman mencapai 1,09 juta kunjungan, jumlah perjalanan wisnus 126,34 juta [Official Statistics News Release]. Accessed November 5, 2026, from https://www.bps.go.id/id/pressrelease/2026/05/04/2568/
- Badan Pusat Statistik. (2026b, June 2). April 2026, kunjungan wisman di Indonesia mencapai 1,25 juta kunjungan, jumlah perjalanan wisnus 97,55 juta [Official Statistics News Release]. Accessed November 5, 2026, from https://www.bps.go.id/id/pressrelease/2026/06/02/2585/
- Badan Pusat Statistik. (2026c, April 30). Statistik wisatawan nusantara 2025. Accessed November 5, 2026, from https://www.bps.go.id/id/publication/2026/04/30/06948320ebe75b7678b09c56/statistik-wisatawan-nusantara-2025.html
- Bank Indonesia. (2026, October 8). Survei Konsumen September 2026: Keyakinan konsumen tetap terjaga [Press Release No. 28/216/DKom]. Accessed November 5, 2026, from https://www.bi.go.id/id/publikasi/ruang-media/news-release/Pages/sp_2821626.aspx
- ANTARA News. (2026, February 2). Kunjungan wisman sepanjang 2025 capai 15,39 juta, didominasi ASEAN. Accessed November 5, 2026, from https://www.antaranews.com/berita/5390738/kunjungan-wisman-sepanjang-2025-capai-1539-juta-didominasi-asean?page=2
- Jakpat. (2026a, August 10). Music concert trends & fan behaviors 2026. Jakpat Insight. Accessed November 5, 2026, from https://insight.jakpat.net/music-concert-trends-fan-behaviors-2026/
- Jakpat. (2026b, August 13). 2026 music trends snapshot: Local artists lead, fans go digital. Jakpat Insight. Accessed November 5, 2026, from https://insight.jakpat.net/2026-music-trends-snapshot-local-artists-lead-fans-go-digital/
- Jakpat. (2026c, October 31). Data plan prices are rising? We don’t leave, we just downgrade. Jakpat Insight. Accessed November 5, 2026, from https://insight.jakpat.net/data-plan-prices-are-rising-we-dont-leave-we-just-downgrade/
- Jenius. (2026a, February 26). Jenius Study 2026: Perilaku traveling lintas generasi. Accessed November 5, 2026, from https://www.jenius.com/article/detail/jenius-study-2026-traveling
- Jenius. (2026b). Jenius Study 2026 [Booklet]. Accessed November 5, 2026, from https://assets.jenius.com/assets/2026/03/09070347/JENIUS-STUDY-2026.pdf
- PwC Indonesia. (2026, September 3). Masyarakat Indonesia semakin mengandalkan teknologi, sumber terpercaya dan komunitas dalam menjalani gaya hidup yang lebih sehat, menurut survei PwC [Press Release]. Accessed November 5, 2026, from https://www.pwc.com/id/en/media-centre/press-release/2026/indonesian/voice-of-the-consumer-survey-2026.html
- Rendanianti, A. (2026, August 15). Cari hiburan jadi alasan utama Gen Z nonton konser musik 2026. GoodStats Data. Accessed November 5, 2026, from https://data.goodstats.id/statistic/cari-hiburan-jadi-alasan-utama-gen-z-nonton-konser-musik-2026-tedUR
- Simamora, N. (2026, May 11). Mandiri Spending Index Mei 2026 melandai, masyarakat mulai rem belanja pasca Lebaran. Kontan. Accessed November 5, 2026, from https://nasional.kontan.co.id/news/mandiri-spending-index-mei-2026-melandai-masyarakat-mulai-rem-belanja-pasca-lebaran
- United Overseas Bank. (2026, July 24). ASEAN Consumer Sentiment Study 2026 (Regional): Consumer confidence remains resilient across ASEAN. UOB ASEAN Insights. Accessed November 5, 2026, from https://www.uobgroup.com/asean-insights/articles/acss-2026-regional.page
- YouGov. (2026, May 8). Rising fuel prices are reshaping spending and mobility habits in Indonesia. Accessed November 5, 2026, from https://yougov.com/articles/54720-rising-fuel-prices-are-reshaping-spending-and-mobility-habits-in-indonesia